Low Appraisal. Now What?
The Appraisal Came in Low. Now What? An Illinois Buyer’s Game Plan
You survived the bidding, the inspection, and your lender asking for the same bank statement three separate times. Then your phone rings: the appraisal came in under your purchase price. Cue the stomach drop.
Before you start drafting a strongly worded email to an appraiser you’ve never met, put the phone down and pick up two things: your contract and the full appraisal report. A low appraisal is one professional’s opinion of value on one date. What you can actually do about it lives in the paperwork, not the panic.
The Short Version
A low appraisal does not automatically cancel an Illinois purchase contract. You generally have four moves: renegotiate the price, bring more cash, ask your lender to reconsider the value, or walk away (only if your contract gives you that right and you use it on time). Which of those doors are open depends on your financing language, any appraisal addendum, your deadlines, and whether the lender denied the loan or just approved a smaller one.
That’s the answer. Now here’s why it plays out the way it does.
Okay, here’s what a low appraisal actually looks like
Say you’re under contract on a house in Algonquin for $425,000, putting 10% down on a conventional loan. The appraisal comes back at $410,000.
Most lenders base the loan on the lower of the price or the appraised value (confirm exactly how yours does it). So your 10% down is now figured on $410,000, not $425,000:
| Loan you planned on (90% of $425,000) | $382,500 |
| Loan the lender will now make (90% of $410,000) | $369,000 |
| Cash you planned to bring for down payment | $42,500 |
| Cash you’d now need at the same $425,000 price | $56,000 |
| Extra cash needed (before closing costs) | $13,500 |
So that $15,000 gap isn’t a $15,000 problem. It’s about a $13,500 one, plus the closing costs you were already paying. Apparently appraisal math doesn’t fit on a refrigerator magnet either. Your loan program and down payment will change these numbers, which is exactly why you run your math, not mine.
Your four options (and who actually gets a vote)
1. Renegotiate the price
You and the seller decide. The seller can say no unless your contract forces the issue.
2. Cover the gap with cash
You and your lender. Depends on your reserves, loan terms, and your honest view of the value.
3. Challenge the value
The lender runs it, with the appraiser. You bring facts: errors and missed comparable sales.
4. Terminate the contract
Only if your signed contract gives you the right, with proper written notice, before the deadline.
These aren’t pick-one-only. In real life, you’re often working two or three of them at the same time.
Can you ask the seller to lower the price?
Yes, you can ask. Asking well is the part that matters. “The appraiser says it’s worth less” lands a lot better when it comes with the actual report and the sales behind it than when it shows up as a vibe. And sellers in our area still hold a fair amount of leverage, as I covered in why the NW suburbs are in a sweet spot for sellers, so expect a negotiation, not an automatic discount.
A seller credit is a different tool than a price cut, and lenders have their own rules about credits. Ask yours before you build a deal around one. (Sellers, your side of that conversation is in should you pay for your buyer’s closing costs.)
Should you cover the gap yourself?
Can you? Maybe. Should you? Only if the numbers work for you and you still believe the house is worth the price on its own merits.
Before you say yes, line up the gap next to your cash reserves, the repairs you already know are coming after closing, and a conservative opinion of what this house is worth. Would I do it? Only if I’d still feel good about the price after the excitement wore off. A lender agreeing to close the loan is not the lender agreeing the price is right. That part is your call.
Can you challenge a low appraisal?
You can ask your lender to start what’s called a reconsideration of value, or ROV. The key word there is lender. Not you, not me, not your cousin who watched a lot of HGTV. The lender controls the review.
For loans that follow Fannie Mae guidelines, the rules are pretty specific: one borrower-requested reconsideration per appraisal report, and you can submit no more than five additional comparable sales (Fannie Mae). The lender reviews the request, decides whether there’s enough to send to the appraiser, and handles the response. Other loan programs have their own process, so ask your lender how theirs works and how long it takes.
What actually helps:
- Recent closed sales nearby that are truly similar (size, age, style, lot, condition, location) that the appraiser didn’t use
- Corrections to square footage, bedroom or bath count, finished space, updates, or site features
- Information the appraiser may not have had when the report was written
- A clear explanation of why the chosen comps or adjustments don’t fit this house
What doesn’t help: “But we really love it.” I know. I believe you. The appraiser doesn’t care. A well-built request can still come back unchanged, so don’t hang your entire strategy on it.
Can you just walk away?
Only if your signed contract gives you a termination right tied to financing or appraisal, and you use it on time with proper written notice (usually through your attorney). This is where earnest money can get at risk. Have your Illinois real estate attorney read the contract, any addenda, and the dates before you refuse to close or let a deadline slide by. A text from your agent or a Reddit thread is not legal review.
The deadline is the boss of this whole situation
Here’s the part nobody tells you: the clock in your contract can run out faster than an appraisal dispute gets resolved. The date that matters is the one printed in your contract, not the day you got the bad news and not the day you finally felt ready to deal with it.
That’s why I run these as parallel tracks. Ask the lender about a reconsideration, talk price with the seller, check your reserves, and get the contract reviewed, all at once. Waiting for the ROV to come back before looking at your deadline is how buyers quietly lose options they didn’t know they had.
Where people get tripped up
“My financing contingency covers this.” Maybe. A contingency tied to the lender denying your loan may not work the same way when the lender approves a smaller loan. The wording matters more than the headline.
“The lender approved it, so the price must be fine.” The lender will lend what it will lend. Whether the price makes sense for you is a separate question.
“My agent can make the lender fix it.” I can help you build the evidence and negotiate with the seller. The formal review belongs to the lender.
What this doesn’t mean
A low appraisal doesn’t mean you picked a bad house, and it doesn’t mean the seller was greedy. It’s one opinion of value, built from the sales available on that date. It also doesn’t mean you get a free exit. Whether you can walk without consequences comes down to your signed agreement, your notices, and what the lender actually decided.
What this looks like around Algonquin and Crystal Lake
Realtor.com’s McHenry County data showed median days on market of about 25 in Algonquin and 30 in Crystal Lake for October 2026. Translation: homes here are still moving at a steady clip. That tells you how long houses take to sell. It does not tell you whether your appraisal is right or whether your seller will budge.
Statewide, Illinois REALTORS reported 25,008 homes for sale in October 2026 versus 24,904 a year earlier. That’s basically flat, and it’s a statewide number, so it says very little about one specific house on one specific street in McHenry County. One number doesn’t tell the whole story. Closed sales of homes like yours do, and that’s the first thing worth gathering when the appraisal comes in short.
Your One Thing
Find the financing or appraisal deadline in your contract and put it in your phone today, before you do anything else.
Holding a low appraisal right now? Bring me the report and your contract, and we’ll figure out which of these four doors are actually open for you, before the calendar starts closing them.
Still in planning mode? That works too. No pressure, just real information.
Book a strategy sessionFree consultation?Questions people actually ask
Does a low appraisal cancel my contract in Illinois?
Not automatically. What happens next depends on your financing language, any appraisal addendum, your deadlines, and whether the lender denied the loan or approved a smaller one.
How much extra cash will I need?
Usually less than the full gap, but more than zero. Because your down payment percentage is typically figured on the lower appraised value, the extra cash depends on your loan program and down payment. Have your lender run the exact number.
How many comps can I send to challenge the appraisal?
For loans following Fannie Mae guidelines: one reconsideration request per appraisal report, with up to five additional comparable sales. The lender reviews it, not you or your agent. Other loan programs may differ.
Can I back out after a low appraisal?
Only if your contract gives you that right and you act within the deadline with proper notice. Earnest money can be on the line, so have your Illinois real estate attorney review it first.
What if the seller won’t lower the price?
Unless your contract says otherwise, they can decline. Then your options are covering the gap, pursuing a reconsideration, or terminating if you still have that right. Weigh the cash option against your reserves and your honest opinion of the home’s value.
Curious how past clients felt about working with us? Read our reviews on Google and Zillow.
About The Jones Team Realtors
The Jones Team has been helping people buy and sell homes across the Fox River Valley since 1976. That’s 2,482 recorded transaction sides and $588,853,034 in combined lifetime sales volume (as of November 2026). Our history runs deepest in Carpentersville, Elgin, West Dundee, Algonquin, Sleepy Hollow, East Dundee, Lake in the Hills, Huntley, Crystal Lake, and Gilberts, so odds are we’ve seen a low appraisal or two on your street.
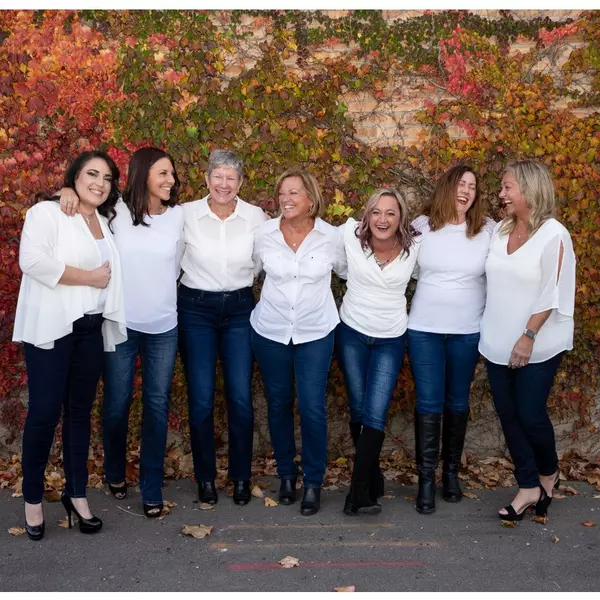
Meet the team:
- Jenny Jones, Team Leader & Broker Associate
- Hilda Jones, Team Founder
- Kim Kern, Broker Associate
- Rita Moehler, Broker Associate
- Sheri Jonas, Broker Associate
- Stephanie Hilbert, Broker Associate
- Emaly Acevedo, Broker Associate
The Jones Team Realtors at Baird & Warner · 1557 S. Randall Rd, Algonquin, IL 60102 · 847.654.9776 · jonesteamhomes.com
Sources: Fannie Mae, Reconsideration of Value · Fannie Mae Selling Guide B4-1.3-12 · Illinois REALTORS · Realtor.com McHenry County market data, October 2026. Last reviewed November 21, 2026.
This article is general information, not legal, tax, or financial advice. Confirm your own numbers and contract rights with your attorney, lender, or tax advisor. Information provided is not guaranteed and subject to change and withdrawal without notice. This publication is not intended to solicit the listing of properties currently under contract with other real estate professionals. We do business in accordance with the Federal Fair Housing Act and the Illinois Human Rights Act. Equal Housing Opportunity. Jenny Jones, Team Leader & Broker Associate, Baird & Warner, 1557 S. Randall Rd, Algonquin, IL 60102. IL License 471.001637.
Categories
Recent Posts


It's EASIER to Move When The Jones Team Has Your Back!
+1(224) 622-3237 | jones.team@bairdwarner.com