How Much Do You ACTUALLY Need to Buy a House?
The Money You ACTUALLY Need to Buy a House
Jenny Jones, The Jones Team at Baird & Warner | 9 min read | Last reviewed: September 2026
The Short Version
There is no single savings number that every buyer needs before purchasing a home.
Your actual amount will depend on things like your purchase price, loan program, down payment, closing costs, negotiated credits, property and personal financial situation.
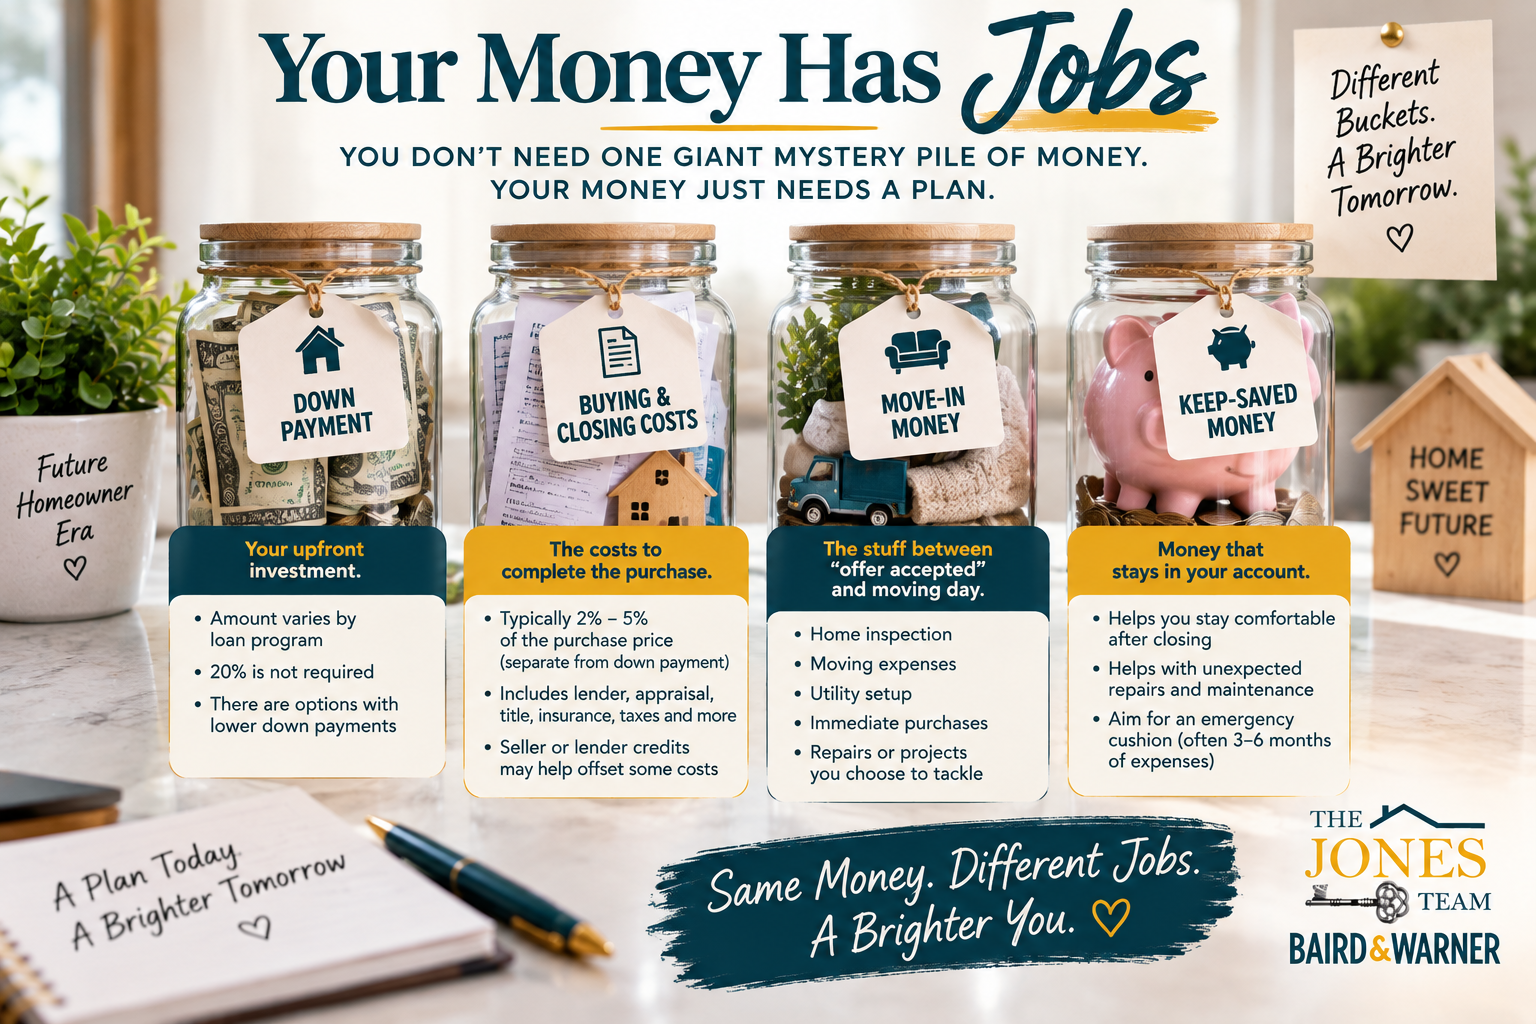
But for planning purposes, it helps to think about your money in four different buckets:
Down Payment
The portion of the purchase price you’re paying upfront.
Buying & Closing Costs
The expenses involved in financing and completing the purchase.
Getting Into the House
Things like inspections, moving and other expenses surrounding the purchase.
Money You Keep
Savings you don’t plan to spend on the transaction.
That last bucket matters more than people sometimes realize.
The goal isn’t just to somehow drag yourself across the closing table with $14.37 left to your name.
The goal is to become a homeowner without immediately becoming terrified of your water heater.
There’s a number floating around in the head of almost every future home buyer.
It’s usually large.
It’s usually intimidating.
And it’s usually based on some combination of things they heard from their parents, TikTok, a coworker who bought a house in 2017, and that one friend who suddenly became a mortgage expert after closing on exactly one property.
It’s the giant mystery pile of money you supposedly need before you’re even allowed to think about buying a house.
Here’s the problem:
That pile isn’t really a thing.
The money involved in buying a home doesn’t all do the same job.
Some may become your down payment. Some handles the costs of actually buying the property. Some gets you through inspections, moving and those first few weeks of homeownership. And ideally, some stays exactly where it is—in your bank account.
So instead of asking:
“How much money do I need to buy a house?”
Let’s ask a much better question:
“What does my money need to DO?”
Because once you understand that, saving for a future home starts feeling a whole lot less mysterious.
Bucket #1: Your Down Payment
We already tackled the giant “YOU NEED 20% DOWN” myth in our article WAIT. WHO TOLD YOU THAT YOU NEED 20% DOWN?.
The refresher version?
Twenty percent is not a universal requirement.
Different mortgage programs have different minimum down-payment requirements, and some qualified buyers may be eligible for options requiring considerably less than 20%.
For example, FHA-insured financing can allow a minimum required investment of 3.5% for eligible borrowers. Other conventional and government-backed programs have their own requirements and eligibility rules.
Putting more money down can have advantages, but “I don’t have 20%” does not automatically mean “I can’t buy a house.”
That’s why your down payment is only one part of your savings plan.
Not the whole enchilada.
Bucket #2: Your Buying & Closing Costs
This is the bucket future buyers sometimes forget exists.
Your down payment goes toward the purchase price of the home.
Closing costs are different.
These are costs associated with obtaining the mortgage and completing the transaction. Depending on your situation, they can include expenses such as:
What closing costs can include
lender or origination chargesappraisal coststitle-related chargesrecording or government feesprepaid homeowners insuranceprepaid interestinitial escrow fundingtaxes and other applicable transaction expensesFor general planning purposes, the Consumer Financial Protection Bureau and Freddie Mac tell buyers to anticipate closing costs that can often fall somewhere around 2% to 5% of the purchase price, separate from the down payment.
But—and this is a very important but—
That is a planning range. It is NOT a quote.
Actual closing costs can vary significantly depending on the property, location, lender, loan program, timing and transaction.
So please don’t whip out the calculator, multiply a random house price by 3%, write it in permanent marker and declare the case closed.
We’re planning here, not tattooing numbers onto anybody.
Wait...Do I Personally Have to Pay Every Closing Cost?
Not necessarily.
Depending on the loan program and transaction, there may be opportunities for things such as seller credits or lender credits to help offset certain closing costs.
That’s useful.
It is not magic.
Seller credits have to be negotiated and may be subject to loan-program limitations. A lender credit can also involve a financial tradeoff—such as accepting a higher interest rate in exchange for reducing certain upfront costs.
So yes, credits can absolutely be part of a home-buying strategy.
But I wouldn’t build your entire Future Home Plan around:
“Eh, somebody else will probably pay it.”
That’s not a plan.
That’s optimism wearing a fake mustache.
Bucket #3: The Stuff Between “Offer Accepted” and “Where Did We Pack the Coffee Maker?”
Not every expense surrounding a home purchase appears neatly under the heading Mortgage Costs.
Real life insists on participating too.
Depending on your purchase, you may want to plan for things like:
- ◆a general home inspection
- ◆specialized inspections when appropriate
- ◆moving expenses
- ◆utility or service setup expenses
- ◆immediate household purchases
- ◆repairs or projects you choose to handle after closing
These aren’t all mandatory mortgage expenses, and every buyer’s situation will be different.
But they’re worth thinking about before you spend every available dollar getting the keys.
Because houses have an uncanny ability to convince perfectly rational adults that they urgently need seventeen things from Home Depot within 48 hours of closing.
You went in for a screwdriver.
You left with a ladder, six lightbulbs, two plants, a shop vac and a receipt for $287.
Welcome to homeownership.
Bucket #4: The Money You DON’T Spend
This one isn’t nearly as exciting as the down payment.
It’s also incredibly important.
Ideally, buying your home doesn’t require draining every account you own.
There is a difference between:
“Can I technically get myself to the closing table?”
and
“Can I comfortably become a homeowner?”
When you’re figuring out how much of your savings could eventually go toward buying, you also want to consider what you’ll need after closing.
That can include your normal monthly expenses, unexpected repairs, maintenance and good old-fashioned life happening at inconvenient times.
The Consumer Financial Protection Bureau encourages prospective buyers to consider an emergency cushion when deciding how much cash they can comfortably put toward a home purchase, commonly referencing three to six months of expenses as a general emergency-savings guideline.
That doesn’t mean every future buyer must have exactly six months sitting untouched before they’re “allowed” to buy.
Your financial situation is yours.
The point is simpler:
Don’t automatically assume every dollar you’ve saved belongs to the house.
Some money may have another very important job:
keeping Future You comfortable after you get the keys.
So...What the Heck Is “Cash to Close”?
You’ll eventually hear this phrase during the mortgage process.
And no, it does not mean your lender expects you to arrive at closing with a duffel bag full of twenties.
Cash to Close is the amount you’ll ultimately need to bring to closing after the applicable pieces of your transaction are calculated.
That can include your down payment and closing costs, while also accounting for things such as deposits you’ve already made, seller credits and other adjustments.
Your Loan Estimate will include an Estimated Cash to Close, and later in the transaction your final numbers will be reflected in your Closing Disclosure.
The important lesson right now is:
Your down payment and your cash to close are not necessarily the same number.
You don’t need to memorize the mortgage paperwork yet.
Just knowing that distinction puts you ahead of where a lot of first-time buyers start.
So How Much Money Do YOU Actually Need?
Here’s the annoying-but-accurate REALTOR answer:
It depends.
I know.
Very satisfying.
But there’s a reason nobody can responsibly give every future buyer one magic savings number.
Imagine two people each have $15,000 saved.
Buyer A
$15,000 saved
Buyer A might use one loan program, buy at one price point, receive negotiated credits and have relatively low moving expenses.
Buyer B
$15,000 saved
Buyer B might buy at a different price, choose a different loan structure, have different closing costs and want more money available after closing.
Same savings. Completely different plan.
So instead of staring at your current savings balance and asking:
“Is this enough?”
start asking:
What jobs would this money eventually need to do?
That’s a question you can actually build a plan around.
Where Future Buyers Get Tripped Up
“Wait. I need 20% PLUS all this other money?!”
Nope.
We’ve already murdered that myth and buried it in Blog #2.
Twenty percent is not universally required.
Your actual down payment depends on your financing and circumstances.
“I thought the down payment WAS the money I needed.”
Totally understandable.
It’s probably the number people hear about most.
But the down payment is only one component of the financial picture.
“I’ll just save exactly enough to close.”
Getting through closing is obviously important.
But so is waking up the next morning as a homeowner with enough financial breathing room to handle your regular life.
Closing isn’t the finish line for your bank account.
“The seller can just pay my closing costs.”
Maybe some costs can be offset through negotiated seller credits.
Maybe they can’t.
It depends on the transaction and financing.
We don’t build plans around money that hasn’t actually been negotiated.
“This still sounds like SO MUCH MONEY.”
Maybe.
But here’s the difference:
Before this article, you may have been picturing one enormous, mysterious number.
Now we can break that number into actual jobs.
And once something has a job, you can make a plan for it.
What This Doesn’t Mean
Understanding these four buckets does not mean:
- ✗You need every possible dollar saved before you’re allowed to explore homeownership.
- ✗Every buyer needs the same emergency fund.
- ✗You should drain your savings to create the biggest possible down payment.
- ✗Seller credits are guaranteed.
- ✗There is some magical number where confetti falls from the ceiling and a mortgage lender appears shouting: “CONGRATULATIONS! YOU ARE NOW FINANCIALLY READY!”
Home-buying readiness is more nuanced than that.
Right now, we’re doing something much simpler.
We’re turning a vague someday-goal into something you can actually start planning for.
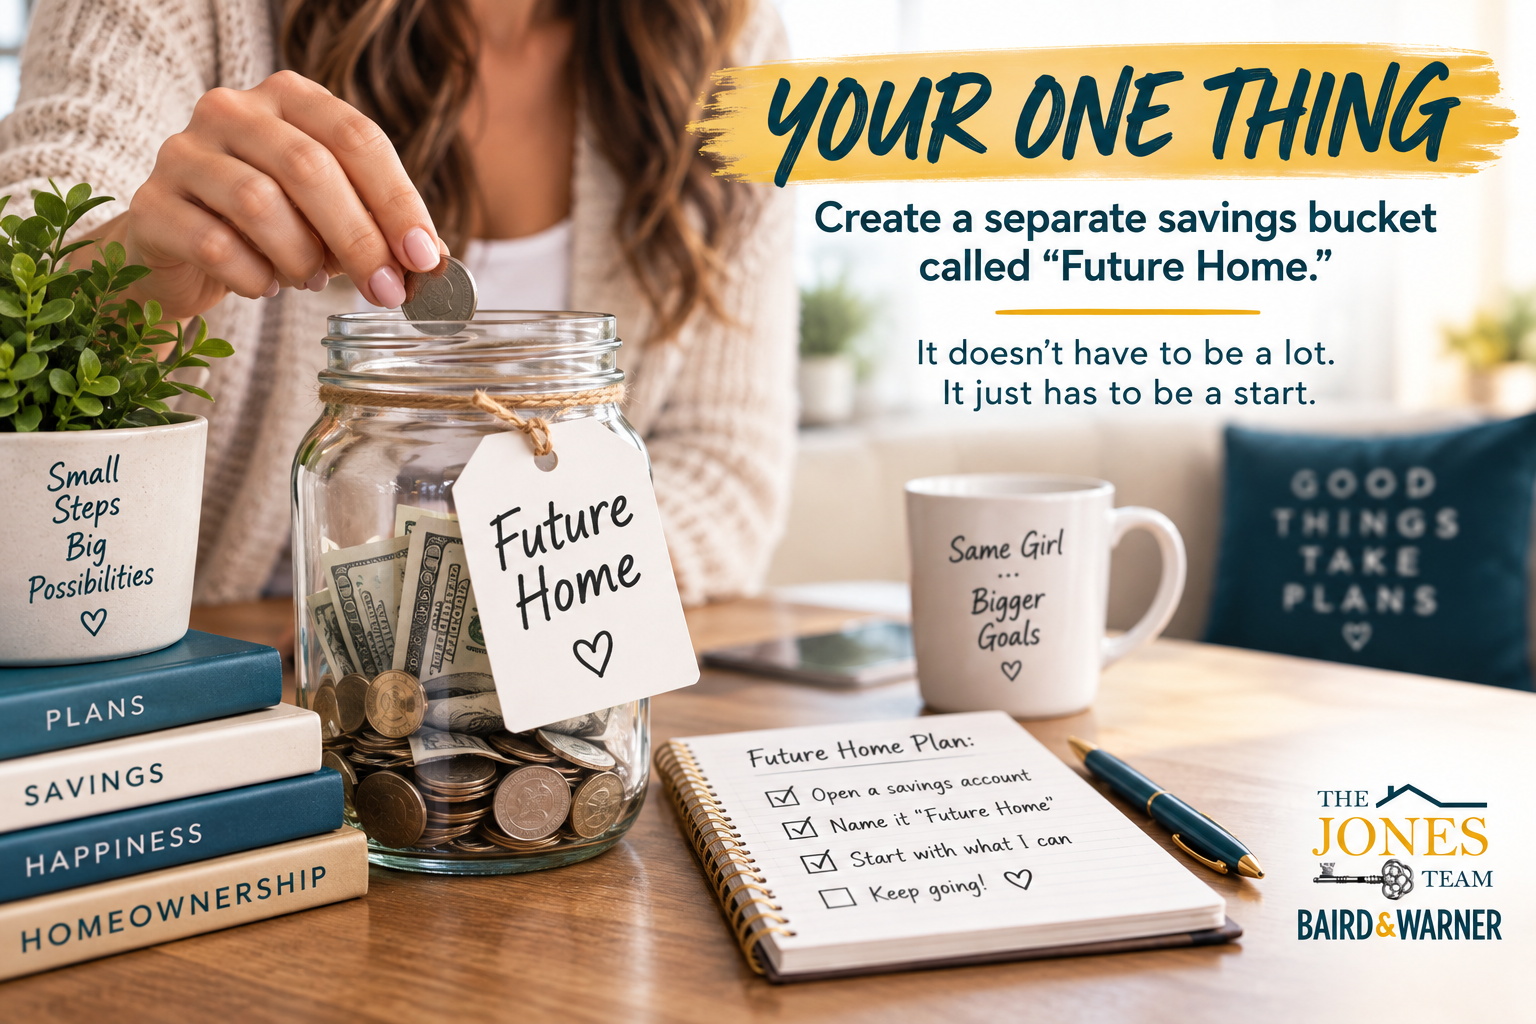
Create a separate savings bucket called “Future Home.”
That’s it.
You don’t need to calculate the perfect amount today.
You don’t need to put $5,000 in it.
You don’t need to know exactly when you’re buying.
Open a separate savings account, create a sub-account or use whatever savings system works for you.
Then name it:
Future Home
Put $25 in there.
Put $100 in there.
Set up a tiny automatic transfer if that’s comfortable for your budget.
The amount isn’t today’s victory.
Creating the bucket is.
Because now you’ve shifted from:
“I’d like to own a home someday.”
to:
“I’m saving for my future home.”
That may sound like a tiny distinction.
It isn’t.
Time required: approximately 30 seconds.
Future Homeowner First. Home Buyer Later.
You don’t need to know your exact purchase price today.
You don’t need to know exactly when you’ll move.
And you certainly don’t need to start touring houses because you opened a savings account on Tuesday.
Right now, your job is simply to start preparing.
Once your savings grows and your timeline becomes clearer, then we can start putting real numbers behind your plan.
Because becoming a prepared homeowner doesn’t begin when somebody hands you a preapproval letter.
It begins much earlier.
Usually with a few small, boring, ridiculously unglamorous decisions that Future You will be very glad you made.
You don’t need one giant mystery pile of money.
Your money just needs jobs.
And now you know what some of those jobs are.
Ready for the Next Small Step?
If owning a home is somewhere in your future—even if that future isn’t next month—start with your Future Home savings bucket.
You don’t need to be ready to buy.
You just need to be ready to prepare.
That’s exactly what the Future Homeowner Plan is for.
Explore the Future Homeowner Plan →Frequently Asked Questions
How much money should I save before buying a house?
There isn’t one amount that works for every buyer. Your savings target depends on your purchase price, loan program, down payment, closing costs, other transaction expenses and how much savings you want to retain after closing. Thinking in separate savings “buckets” can make planning much easier.
Are closing costs separate from the down payment?
Generally, yes. Your down payment is the portion of the purchase price you’re paying upfront, while closing costs are expenses associated with financing and completing the purchase.
How much are closing costs?
The CFPB and Freddie Mac provide a general planning range of roughly 2% to 5% of the purchase price, separate from the down payment. Actual closing costs vary based on the transaction, lender, loan, property and location.
Can the seller pay some of my closing costs?
Seller credits may sometimes be negotiated to offset eligible closing costs, subject to the terms of the contract and applicable loan-program rules. They are not guaranteed.
What does “cash to close” mean?
Cash to Close is the amount you’ll ultimately need to bring to closing after your down payment, closing costs, deposits, credits and applicable adjustments are calculated. Your Loan Estimate will provide an Estimated Cash to Close earlier in the mortgage process.
Should I still have savings after buying a house?
Ideally, your home purchase doesn’t leave you without financial breathing room. How much you should retain depends on your individual circumstances, but it’s wise to consider normal living expenses, home maintenance, unexpected repairs and other emergencies when deciding how much of your savings to put toward the purchase.
Keep Going With the Future Homeowner Plan
◆Article 1: Your Rent Could Actually Help Your Credit
◆Article 2: WAIT. WHO TOLD YOU THAT YOU NEED 20% DOWN?
◆Article 3: What Credit Score Do You REALLY Need?
◆Article 4: Rent vs. Buy: It’s Not Just About the Payment
A Quick Note Before You Go: This article is for general educational purposes and isn’t financial, legal, tax or mortgage advice. Mortgage programs, qualification requirements, down-payment requirements, closing costs, credits and transaction expenses vary based on the borrower, property, lender, loan program and individual transaction. Examples and general ranges are educational only and are not a loan quote, approval or guarantee of financing.
About Jenny Jones & The Jones Team
Jenny Jones and The Jones Team at Baird & Warner help buyers and sellers throughout Chicago’s northwest suburbs and the Fox River Valley navigate real estate with education, strategy and straight answers.
After more than two decades in real estate and hundreds of successful home sales, Jenny & her team believe future buyers shouldn’t have to become mortgage experts before they’re allowed to start preparing for homeownership.
The Future Homeowner Plan was created to help renters take those first steps—one manageable decision at a time.
Sources
- Consumer Financial Protection Bureau — Determine Your Down Payment
- Consumer Financial Protection Bureau — Loan Estimate Explainer
- Consumer Financial Protection Bureau — Figure Out How Much You Want to Spend
- Fannie Mae — What You Need to Know About Down Payments
- Freddie Mac — Understanding Homebuying Costs
- U.S. Department of Housing and Urban Development — FHA Loan Information
Last Reviewed: September 9, 2026
Educational Note: Mortgage programs, underwriting requirements, interest rates and lender
guidelines can change and may vary based on the borrower, property, loan program and
lender. This article is intended for general educational purposes and is not financial, credit,
lending or legal advice. A licensed mortgage professional can evaluate your individual
circumstances and current financing options.
Categories
Recent Posts


It's EASIER to Move When The Jones Team Has Your Back!
+1(224) 622-3237 | jones.team@bairdwarner.com