Your Credit DOES NOT Need to be Perfect to Buy a Home
What Credit Score Do You REALLY Need?
Jenny Jones, The Jones Team at Baird & Warner | 6 min read | Last reviewed: September 2026
The Short Version
There isn’t one universal credit score required to buy a home.
Different mortgage programs and lenders have different requirements, and your credit score is only one part of your overall financial picture.
FHA guidelines can allow maximum financing with qualifying scores of 580+, while VA itself doesn’t establish a minimum credit score. Conventional and USDA financing are more nuanced than the single numbers you’ll often see online.
And the credit score showing in your favorite app may not even be the exact score a mortgage lender uses.
Bottom line: Don’t disqualify yourself based on one number. Find out where you actually stand first.
Maybe you’ve already decided your credit isn’t good enough to buy a house.
You checked an app.
You saw a number.
You remembered that one late payment from approximately the Jurassic period.
And somewhere along the way, you heard that you need a 700...or a 720...or a 740...or possibly an 847 and a handwritten recommendation from Experian.
So you did what a whole lot of renters do:
You disqualified yourself before anybody actually qualified you.
Here’s the problem.
There is not one magical credit score that determines whether you can become a homeowner.
Yep.
Another homebuying rule that isn’t nearly as neat and tidy as the internet made it sound.
So...what credit score DO you need?
The mildly annoying but completely accurate answer is:
It depends.
Your credit score matters. Absolutely.
But mortgage approval isn’t based on your credit score alone.
Different loan programs have different guidelines. Different lenders can have different requirements. And when a lender evaluates a mortgage application, they’re looking at a much bigger financial picture that can include things like:
- ◆your credit history,
- ◆your income,
- ◆your existing monthly debts,
- ◆your available funds and assets,
- ◆the type of mortgage you’re using,
- ◆and the overall strength of your application.
In other words:
Your credit score is important.
It is not your entire financial personality.
And that distinction matters.
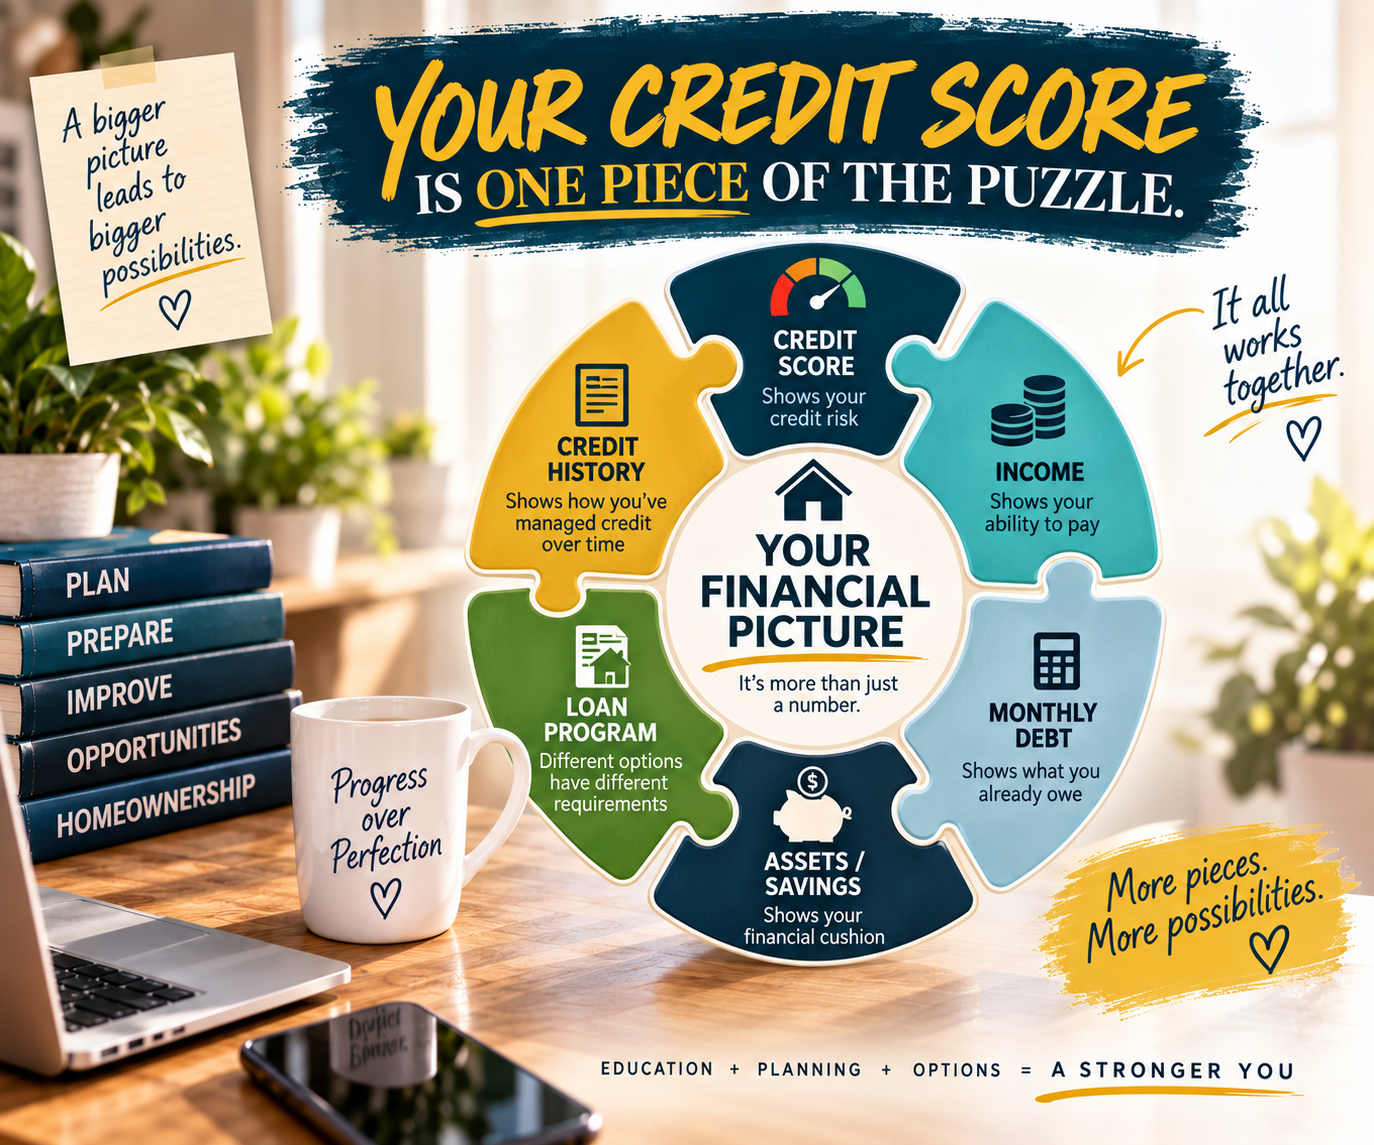
Your credit score is one piece of the puzzle
Your Financial Picture
Credit Score
Credit History
Income
Monthly Debt
Assets / Savings
Loan Program
“But I heard you need at least a 620.”
You’ve probably heard some version of this.
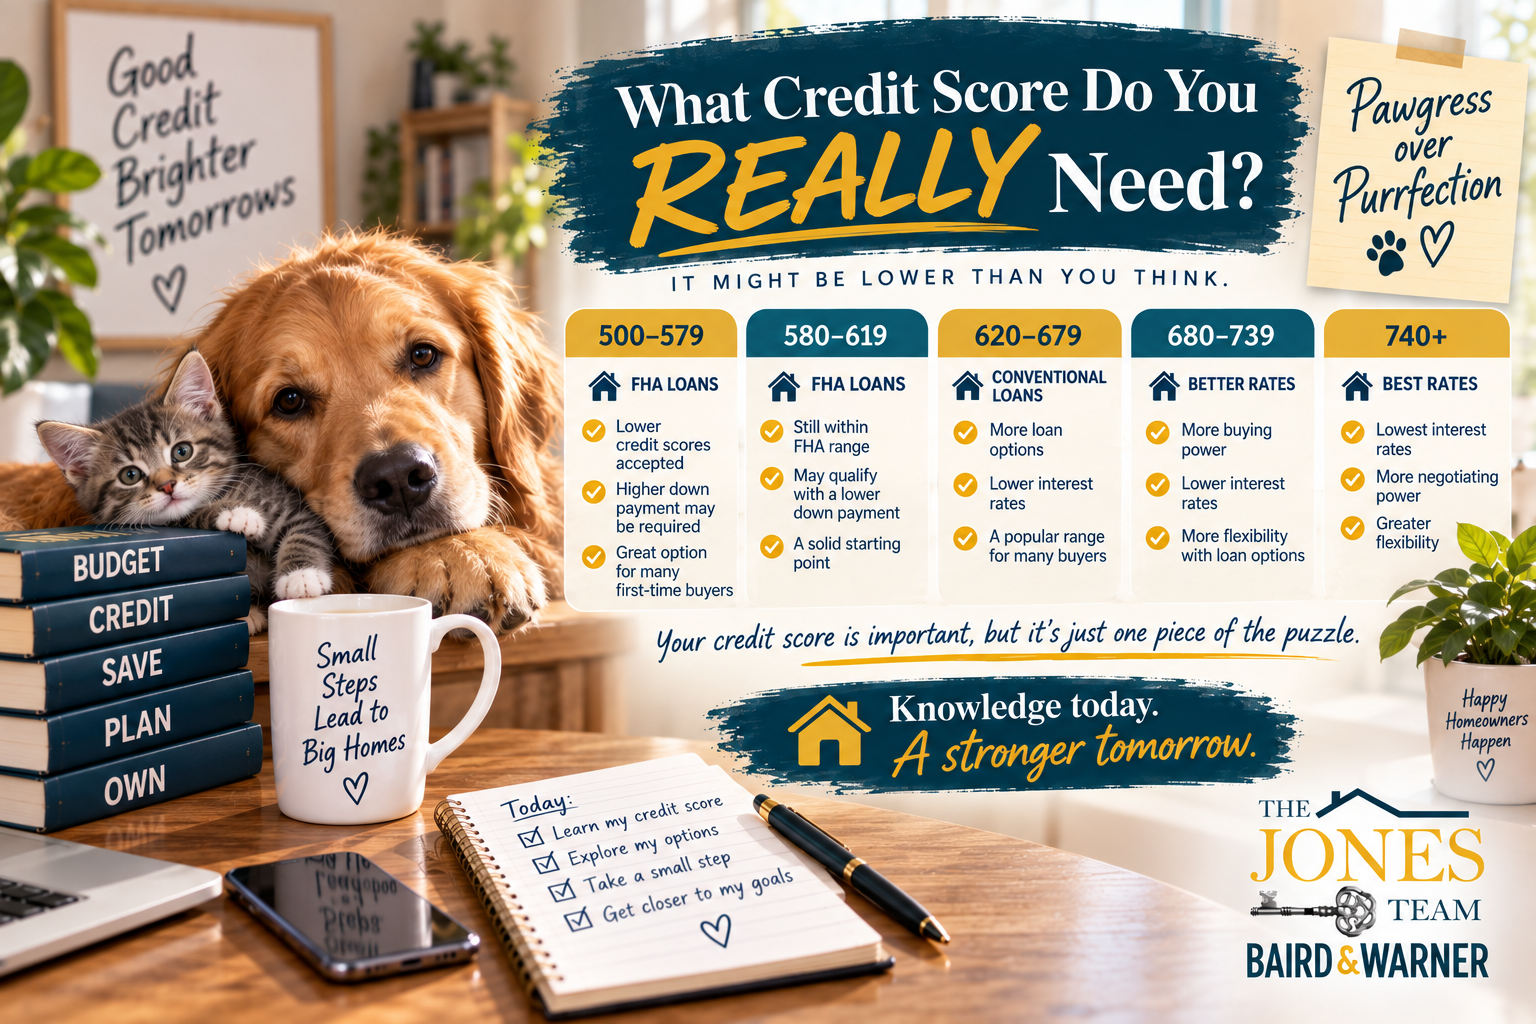
And sometimes numbers like 620 are useful reference points when people talk about conventional financing.
But turning that into:
“Anyone under 620 can’t buy a house.”
is way too simplistic.
Conventional mortgages can be evaluated through automated underwriting systems that consider multiple pieces of the borrower’s financial profile.
Specific programs and lenders may also have their own requirements.
Translation?
There isn’t one universal conventional mortgage number that answers every borrower’s situation.
This is exactly why Googling “What credit score do I need to buy a house?” can produce seventeen answers before breakfast.
They’re often talking about different loans, different underwriting situations and different lender requirements.
FHA gives us a clearer example.
FHA financing is commonly used by buyers who may have less money saved or credit that isn’t perfect.
Current FHA guidelines generally allow maximum financing for borrowers with qualifying credit scores of 580 or higher, which can permit a down payment as low as 3.5%.
Scores between 500 and 579 may still fit within FHA guidelines in certain situations, but the maximum loan-to-value is lower—which generally means a larger down payment would be required.
Now before anyone takes that sentence, runs into the street and yells:
“JENNY SAID I CAN BUY A HOUSE WITH A 500!”
No.
Settle down, Sparky.
Those are program guidelines.
A lender still has to approve the loan, and lenders can have additional requirements.
Which brings us to one of the most important things to understand about mortgage credit:
Loan-program rules and lender rules are not always exactly the same.
The loan program
Sets the guidelines.
What the program permits.
The lender
Approves the loan.
Can add requirements on top.
Program eligibility ≠ guaranteed lender approval.
That is why two people with similar credit scores can have very different financing conversations.
VA loans are another great example.
If you’re an eligible veteran, active-duty service member or qualifying surviving spouse, VA financing can offer some incredible benefits.
And here’s something a lot of people don’t know:
The Department of Veterans Affairs itself does not establish a minimum credit-score requirement for VA loans.
Individual lenders, however, can establish their own requirements.
Which once again proves the point:
There is no single three-digit number floating above your head that automatically decides whether you’re allowed to buy a home.
Your situation needs to actually be evaluated.
And USDA isn’t just “you need a 640” either.
USDA financing is another program where you may hear one particular credit score tossed around like it’s a universal rule.
But USDA’s automated underwriting process evaluates the overall loan file, not just one score.
That doesn’t mean credit stops mattering.
It means the answer is more nuanced than:
Score = yes.
or
Score = absolutely not, go back to renting forever.
Mortgage underwriting is rarely that dramatic.
The internet, however?
Very dramatic.
“Okay, but my app says my score is 672.”
Great.
That is useful information.
But here’s something most consumers don’t realize:
You don’t have just one credit score.
There are different scoring models.
Different lenders can use different versions.
Scores can also vary depending on which credit bureau supplied the information and when the score was calculated.
Mortgage lenders commonly use FICO credit scores pulled from the major credit bureaus as part of their evaluation.
That means the score you see in a free consumer app may not be identical to the score a mortgage lender sees.
Your app isn’t necessarily wrong.
It just isn’t sitting at the closing table holding your mortgage documents.
So if you’ve been staring at one number on your phone and using it to decide:
“Nope. I definitely can’t buy.”
you may be making a pretty large financial assumption with incomplete information.
There are actually TWO credit questions future homeowners should ask.
Most people only ask:
“Is my credit good enough to qualify?”
That’s an important question.
But there’s another one that can be just as valuable:
“Would improving my credit put me in a better buying position?”
Because credit isn’t only about getting approved.
Credit can also affect things like your mortgage options, your interest rate and ultimately how much borrowing costs you.
Generally, stronger credit can give borrowers access to better loan choices and potentially better pricing.
So imagine three future homeowners:
Buyer #1
may already be in a perfectly workable position today.
Buyer #2
may qualify today—but could improve their financing options by working on credit for a few months.
Buyer #3
may need some additional time and a specific plan before buying makes sense.
None of those people failed.
They just have different starting points.
And knowing which one you are is a whole lot more useful than guessing.
Please stop trying to become your own mortgage underwriter.
I say this lovingly.
You do not need to spend six months reading Reddit threads, watching TikToks and reverse-engineering FICO algorithms before you’re allowed to ask questions about buying a house.
You also shouldn’t randomly start:
- ◆paying off every account,
- ◆closing credit cards,
- ◆opening new credit,
- ◆moving balances around,
- ◆or making major financial changes
because somebody on the internet said it would “boost your score fast.”
Some financial moves can affect mortgage qualification in ways you may not expect.
That’s why the smartest first move isn’t:
“FIX EVERYTHING.”
It’s:
Find out where you actually stand.
Maybe you’re ready.
Maybe you’re close.
Maybe you need a little time.
All three answers are valuable because now you’re working from information instead of assumptions.
Where People Get Tripped Up
People commonly:
Assume a score they saw online is their mortgage score.
Consumer apps and mortgage lenders don’t always use the same scoring model, bureau data or timing.
Believe one universal score applies to every mortgage.
FHA, conventional, VA and USDA each treat credit differently—and so do individual lenders.
Confuse loan-program guidelines with individual lender requirements.
A program can permit something while a lender still maintains additional requirements.
Assume “eligible” means “automatically approved.”
Program eligibility is a starting point. A lender still has to approve the loan.
Focus only on qualifying instead of considering loan pricing and options.
Credit can affect your mortgage options and your interest rate, not just the yes/no.
Make random credit moves before understanding how those decisions could affect mortgage qualification.
Some moves can change your picture in ways you may not expect. Know your starting point first.
They self-disqualify before ever getting real information.
What This Doesn’t Mean
This article does NOT mean “credit doesn’t matter.” It absolutely does.
It also doesn’t mean:
- ✗“Anyone with a 580 can buy a house.”
- ✗“Anyone with a 500 can get FHA financing.”
- ✗“If a loan program allows something, every lender will.”
- ✗“Don’t worry about improving your credit.”
Our message is much more responsible:
Your credit matters—but one number doesn’t tell your entire homebuying story.
Find out where your credit actually stands before deciding what it means.
That’s it.
You do not need perfect credit today.
You do not need to know every mortgage rule.
And you definitely do not need to spend tonight panic-Googling “How fast can I raise my credit score 100 points?”
Your job right now is simply to stop self-disqualifying.
Get the real information.
Then decide what the next move should be.
Ready now?Improve first?Make a plan?
Time required: approximately 30 seconds. All three paths lead forward.
Future Homeowner Homework 📝
Take five minutes and write down the answer to this question:
What credit score do I THINK I need before I could buy a home?
Then underneath it write:
Where did I get that number?
Was it from a lender?
A real mortgage evaluation?
Or was it something you heard from a friend, saw online or absorbed somewhere between TikTok and the comments section?
You may discover that one of the biggest things standing between you and a future home isn’t your credit score.
It’s an assumption.
And assumptions are considerably easier to fix.
The Future Homeowner Bottom Line
You don’t need to know today whether you’ll buy a home next month, next year or three years from now.
That’s not what the Future Homeowner Plan is about.
It’s about turning:
“I probably can’t.”
into:
“Let’s actually find out.”
Because once you know where you really stand, you can make a plan.
And plans?
Those are a whole lot more useful than imaginary rejection letters you wrote yourself.
Not sure whether your credit is actually standing between you and homeownership? Let’s find out before you assume it is.
The Jones Team can help you understand what the homebuying process looks like, connect you with trusted lending resources when you’re ready, and help you build a realistic path forward.
No house hunting required. No pressure. Just real information.
Explore the Future Homeowner Plan →Credit Score FAQ
What credit score do you need to buy a house?
There isn’t one universal minimum. Requirements vary by mortgage program, lender and overall borrower profile.
Can you buy a house with a 580 credit score?
FHA guidelines allow borrowers with qualifying scores of 580 or higher to potentially receive maximum FHA financing, subject to the rest of the loan requirements and lender approval.
Can you get an FHA loan with a credit score below 580?
FHA guidelines permit scores from 500–579 in certain circumstances but limit maximum financing to 90% LTV. Individual lenders may impose additional requirements.
Do VA loans have a minimum credit score?
The Department of Veterans Affairs itself does not establish a minimum credit score, although individual VA lenders can establish their own credit requirements.
Is the credit score on my app the same one a mortgage lender will see?
Not necessarily. Consumers can have multiple credit scores based on the scoring model, bureau, timing and purpose for which the score is calculated.
Does a higher credit score help you get a better mortgage rate?
Generally, stronger credit can improve mortgage options and pricing, although your actual rate and terms depend on multiple factors.
Keep going in the Future Homeowner Plan
◆Article 1: Your Rent Could Actually Help Your Credit
◆Article 2: WAIT. Who Told You That You Need 20% Down?
◆Article 4: Coming next — mortgage readiness, debt-to-income and what lenders look at beyond your score
Educational Note: Mortgage programs, underwriting requirements, interest rates and lender
guidelines can change and may vary based on the borrower, property, loan program and
lender. This article is intended for general educational purposes and is not financial, credit,
lending or legal advice. A licensed mortgage professional can evaluate your individual
circumstances and current financing options.
About The Jones Team
The Jones Team at Baird & Warner helps buyers throughout Chicago’s northwest suburbs understand the homebuying process before they’re expected to make big decisions. Led by Jenny Jones, a REALTOR® with more than 20 years of experience and 400+ homes sold, the team’s approach is simple: education first, pressure never.
The Future Homeowner Plan was created to help today’s renters understand what actually goes into becoming tomorrow’s homeowners—one manageable step at a time.
Sources
- U.S. Department of Housing and Urban Development — FHA Single Family Housing Policy Handbook
- Consumer Financial Protection Bureau — mortgage and credit-score guidance
- Fannie Mae Selling Guide — credit-score requirements
- Freddie Mac Single-Family guidance
- U.S. Department of Veterans Affairs — VA Home Loan guidance
- USDA Rural Development — Guaranteed Underwriting System guidance
Educational Note: Mortgage programs, underwriting requirements, interest rates and lender
guidelines can change and may vary based on the borrower, property, loan program and
lender. This article is intended for general educational purposes and is not financial, credit,
lending or legal advice. A licensed mortgage professional can evaluate your individual
circumstances and current financing options.
Last reviewed for program accuracy or availability: September 9, 2026
Categories
Recent Posts


It's EASIER to Move When The Jones Team Has Your Back!
+1(224) 622-3237 | jones.team@bairdwarner.com